The Money Lessons Every Parent Should Pass On to Their Kids: An Age-by-Age Guide
From preschool coin-sorting to teen paychecks, here's what child-development research says about teaching money skills at every age — and why the lessons matter.
Why Money Conversations Can't Wait
Many parents assume financial literacy is a topic for the teenage years — maybe around the time of a first job or a driver's license. But research suggests the groundwork is laid much earlier. Research from the University of Cambridge shows money habits are set by the age of seven, though parents have real power to foster financial literacy at home throughout kids' lives in various ways.
The good news is that you don't need a finance degree to raise a money-smart kid. The Consumer Financial Protection Bureau (CFPB) has spent years researching how children develop financial capability, and its findings offer a helpful roadmap — one that breaks the journey into three broad developmental stages, each with its own focus and vocabulary.
Ages 3–5: Building the Foundation
According to the CFPB, executive functioning emerges in early childhood, from ages 3–5 — a set of cognitive processes used to plan for the future, focus attention, remember information, and juggle multiple tasks, which encourages perseverance, self-regulation, and prioritizing future gain over current desires. In plain terms: this is the age to build patience and basic cause-and-effect thinking, not spreadsheets.
What to say and do:
- Say: "You need money to buy things, and you earn money by working."
- Say: "You may have to wait and save up money before you can buy something you want."
- Say: "Every time you spend money, you make a choice. There's a difference between things you need and things you want."
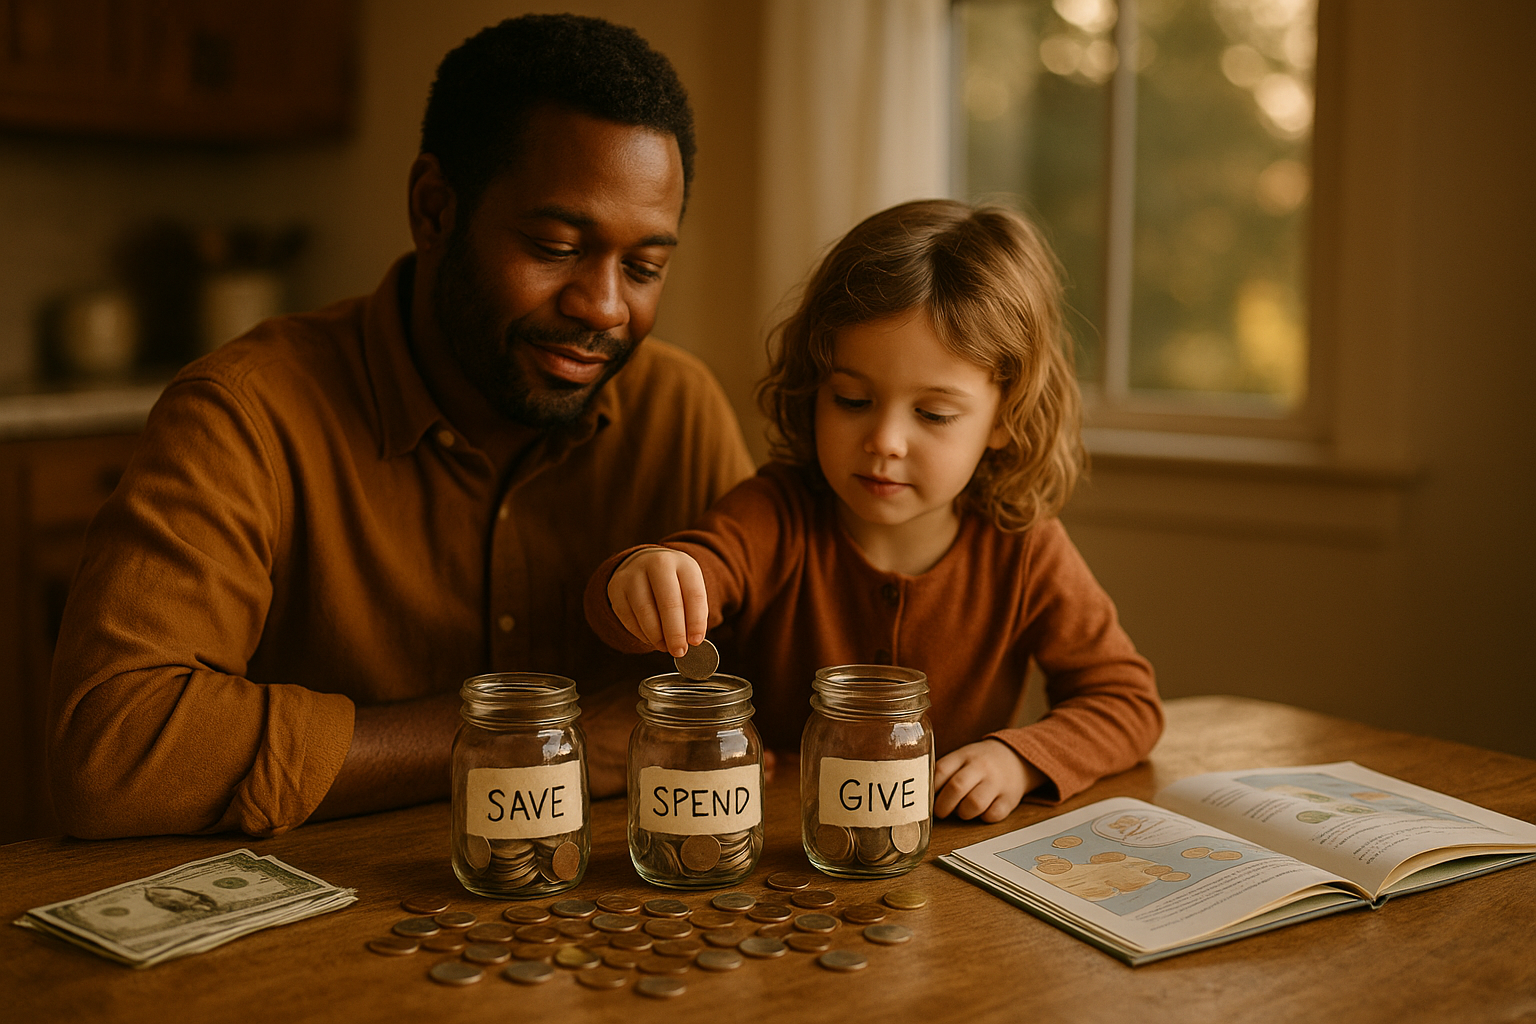
Practical tools help make abstract ideas concrete. Swapping a piggy bank for a clear jar lets a child physically watch savings grow, and letting a preschooler hand a few dollars to a cashier turns a lesson into a lived experience. One useful classroom finding: parents and educators can help nurture executive function by teaching patience and delayed gratification — in one study, preschool children who viewed a video of a character resisting a favorite treat could wait longer for a snack than children who didn't see it. Modeling patience — even narrating your own — genuinely helps.
Ages 6–12: Habits Take Root
This stretch of childhood is where day-to-day money behavior gets wired in. Financial habits and norms emerge in middle childhood, from ages 6–12 — the values, standards, routine practices, and rules of thumb used in daily financial life, which help develop unconscious, automatic decision-making strategies based on attitudes, values, emotions, social norms, and contextual cues.
What to say and do:
- Say: "You can earn money through an allowance or by doing jobs for the family or others."
- Say: "You can start a habit of putting money aside for things you want."
- Say: "You need to make choices about how to spend your money."
Because children often draw their own conclusions from their parents' actions — and sometimes they're not what was intended — try getting into the habit of thinking out loud during day-to-day money and time management so kids can follow along. An allowance tied to chores, a family budgeting conversation before a big purchase, or a trip to open a first savings account can all reinforce the same message: money requires planning and trade-offs.
Ages 13–21: From Knowledge to Real-World Decisions
Adolescence is when financial concepts become financial facts — the kind teens will soon apply on their own. Financial knowledge and decision-making skills emerge in adolescence and young adulthood, from ages 13–21, encompassing familiarity with financial facts and concepts such as skillful money management, financial planning, goal setting, and financial research — concepts that financial literacy education for high schoolers can focus on.
Talking points for teens:
- Many teens at this age are able to understand increasingly complex financial concepts, including borrowing, credit, and making smart investments.
- Reviewing credit card statements together and discussing interest, due dates, and minimum payments helps emphasize the consequences of accruing more debt than can be paid off each month.
- If your teen takes on a job, review their pay stubs together — a first paycheck is a natural opening to talk about taxes, deductions, and net versus gross pay.
- Encourage exploration of banking tools, budgeting apps, or a mock investment portfolio to build comfort before real money is on the line.
The Thread That Runs Through Every Age: You Are the Model
Across all these stages, one theme holds steady: children are always watching. Parents are the primary influence on a child's future financial well-being because they have many occasions to communicate information, set powerful examples, and involve children in activities that teach financial skills — and parental involvement has long-lasting effects. The CFPB puts it simply: your children are constantly watching and listening, so they might absorb more than you think — when you shop for a bargain, splurge on a treat, or plan a special occasion, you're showing your kids how you think about money.
This is also why financial values are rarely taught in a single sit-down talk. They accumulate — in grocery store choices, in family budget conversations, in the quiet example of a parent saving for a goal. And for many families, those small daily lessons blend into something bigger: a philosophy about money, work, and generosity that a child eventually recognizes as "how our family does things."
That's part of why so many parents want to make sure their money values, and the stories behind them, actually reach the next generation — not just the rules, but the why. Recording a few reflections on money mindset, hard-earned lessons, or hopes for a child's financial future is one way families use Voice After Life to preserve not just facts, but the voice and heart behind them, so a child can hear it directly from a parent for years to come.
Financial Literacy Is a Long Game
The data on why this matters is compelling. Financial education has been linked to lower debt levels, higher savings, and higher credit scores as children mature into adulthood, and later in life it's also positively connected to net worth and investing. Yet the starting point doesn't have to be complicated. As one expert summarized it, the message is clear: financial education isn't just about money — it strengthens decision-making, responsibility, and confidence.
Whether your child is stacking coins at age four or reviewing a first pay stub at sixteen, the goal is the same: small, consistent, age-appropriate conversations that turn abstract numbers into lifelong habits — and values worth passing down.
- Voice After Life.com
Sources
- Financial milestones for kids: an age-by-age guide — GoHenry
- An Age-By-Age Guide to Teaching Kids About Money — Southern Bank
- Teaching Children About Money Now, Pays Dividends Later — FDIC
- How to Teach Children Good Financial Habits: CFPB Releases Building Blocks — InCharge Debt Solutions
- Money milestones for teenagers and young adults — Consumer Financial Protection Bureau
- Young children | Money as You Grow — Consumer Financial Protection Bureau
- School-age children to preteens | Money as You Grow — Consumer Financial Protection Bureau
- Money lessons to teach your children at every age — RMIT University